Author: Charlotte

Team update: Dan had a fantastic time celebrating his birthday in October

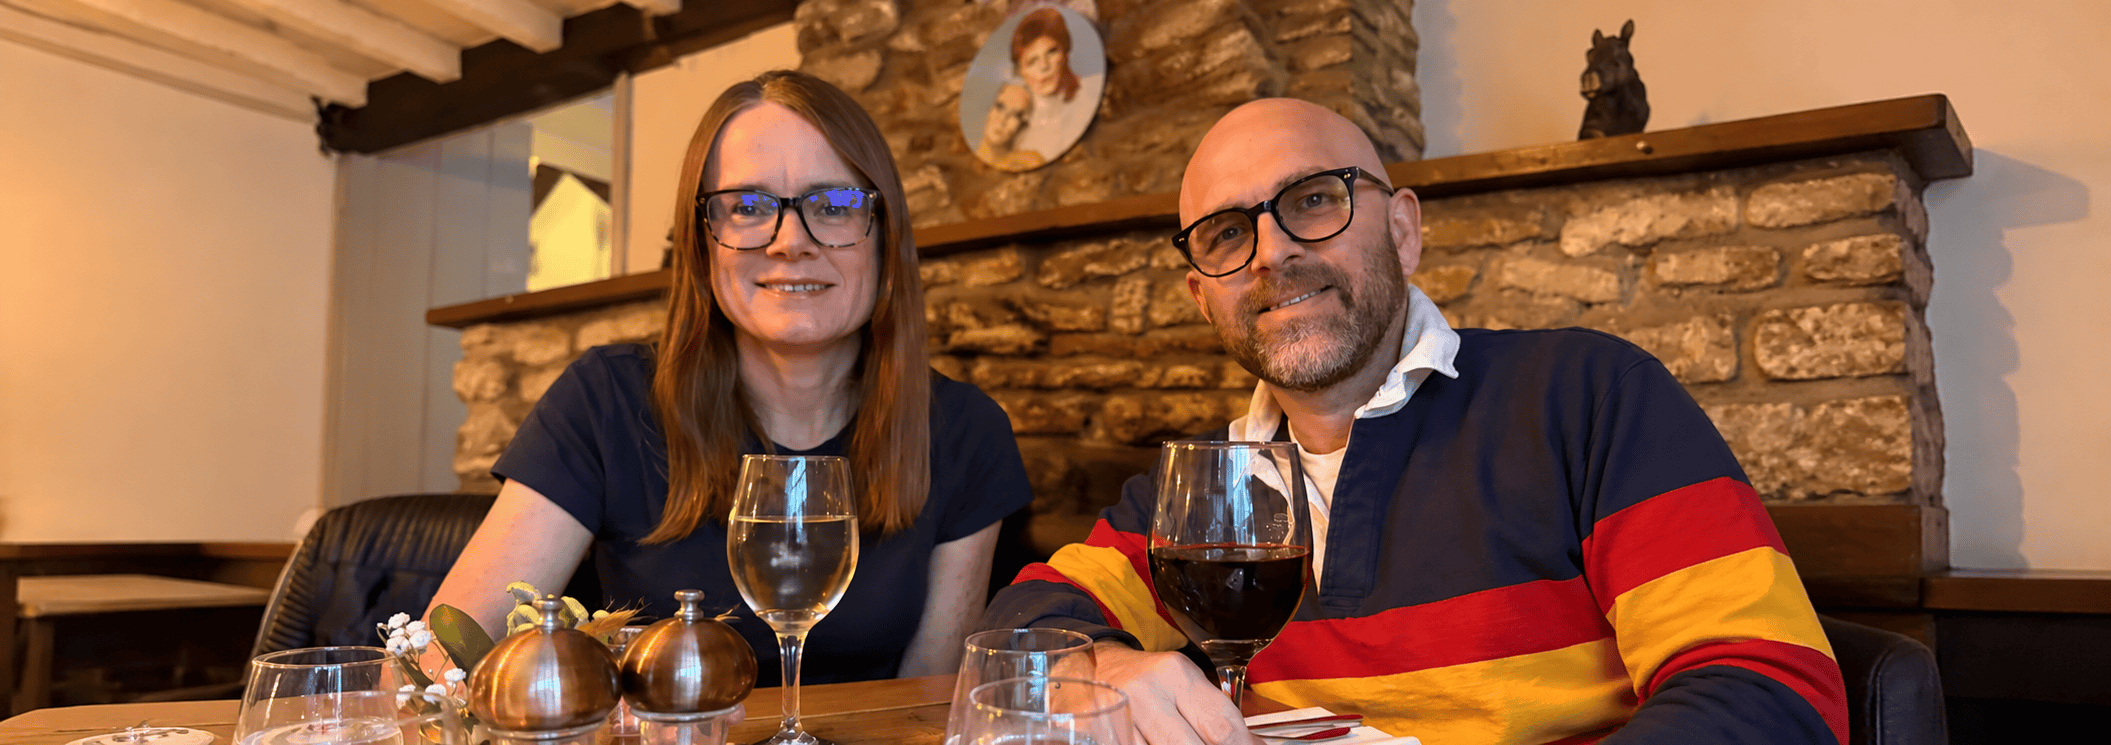
Following Sarah Britton’s big birthday celebrations, this month it’s the turn of our director, Dan Britton, to blow out the candles and enjoy being the centre of attention for a day.

A fabulous day with family

On 1 October, Dan turned 49, and he chose to spend the day locally with his family. 

He and Sarah took the kids to a restaurant in Bristol, where they enjoyed plenty of good food, chat, and laughter. 

Dan said, “We all had a great time. I love being together as a family on my birthday. It was a really relaxed day. As it’s my big birthday next year and we’re planning something special, I wanted to do something low-key near home this year – and it worked out just as I hoped.”

A trip to the rugby

The Brittons are keen sports fans, so, as part of his birthday celebrations, Dan took the kids to watch their first Bristol rugby game at the weekend. 

He loved introducing them to one of his favourite sports. Dan said, “The kids were great. They really enjoyed the game and the atmosphere of being in the stadium. 

“It was a real bonus that we had a great win. The Bristol Bears beat the Northampton Saints – the reigning champions – 41-26!

“We all came away very happy. It was the perfect way to round off my birthday week. 

“I’m really excited for next year too. We haven’t quite decided what to do, but we’ll push the boat out a bit for the big 5-0.” 

Get in touch

If you’d like to learn more about the Blue Wealth team and how we can support you with all your financial planning needs, we’d love to hear from you.

To find out more, please email hello@bluewealth.co.uk or call us on 0117-332 0230.

Please note

The content of this newsletter is offered only for general informational and educational purposes. It is not offered as, and does not constitute, financial advice.

4 scary tax traps to avoid if you’re nearing retirement

Halloween is just weeks away on 31 October. For those approaching retirement, the genuinely frightening things are not monsters under the bed or zombies at the window – they are scary tax traps that could disrupt your plans for this exciting new life chapter.

Seemingly minor financial decisions made just before or during retirement could trigger unnecessary Income Tax, increase your estate’s Inheritance Tax (IHT) liability, or reduce your ability to grow your pension pot tax-efficiently. 

Fortunately, with the right support, advice, and planning, you could avoid these frightful mistakes and protect your retirement funds from avoidable tax.

Read on to discover four common tax traps that catch people out in the run-up to retirement and learn how timely financial advice could help you keep tax nightmares at bay.

1. Exceeding available tax-free allowances for pension withdrawals

You can usually access workplace and private pensions from age 55 (rising to 57 from 6 April 2028). This could provide a valuable source of income before or after you retire. 

However, it’s crucial to understand the tax implications of drawing on your pension.

While the first 25% of your pension pot is typically tax-free up to a limit of £268,275 (the Lump Sum Allowance, or LSA), the taxable portion of your pension is normally subject to Income Tax at your marginal rate. It’s important to note that the 25% threshold applies to your total pension savings, not each individual scheme. Therefore, if you take a lump sum from several pensions without checking how much of your allowance remains, you could be in for a fright when your next tax bill arrives.

You or your beneficiaries may be eligible to take a tax-free lump sum of up to £1,073,100 in certain circumstances, for example, if funds are paid out due to serious illness. This is known as the Lump Sum and Death Benefit Allowance (LSDBA). If you withdraw more than this, you’ll need to pay Income Tax on the amount that exceeds the allowance.

Your LSA and LSDBA may be higher if you hold a protected allowance. It’s worth using the government’s free online tool to check your allowances before planning your pension withdrawals. 

2. Triggering the Money Purchase Annual Allowance

The standard pension Annual Allowance for the 2026/27 tax year is £60,000, which is the maximum that can be contributed to all private and workplace pensions before a tax charge applies. However, if you start making flexible withdrawals of taxable money from a defined contribution (DC) pension, this triggers the Money Purchase Annual Allowance (MPAA).

The MPAA caps the amount you and your employer can contribute to DC pensions in a single tax year without incurring an Annual Allowance tax charge at £10,000. Moreover, once the MPAA has been triggered, it remains in place for life.

As such, if you want to continue topping up your pension after accessing it – for example, because you plan to keep working or running a business – it’s important to factor this into your financial plan. 

3. Losing the Personal Allowance: the 60% tax trap

For 2026/27, most people have a Personal Allowance of £12,570. This is the amount of income you do not have to pay tax on. 

However, your Personal Allowance is reduced by £1 for every £2 that your “adjusted net income” (total taxable income before any Personal Allowances and less certain tax reliefs) exceeds £100,000 in a single tax year. You lose your Personal Allowance altogether if you earn £125,140 or above.

As income between £100,000 and £125,140 falls into the higher-rate Income Tax bracket (40%), for every £100 you earn within this range, you’ll pay £40 Income Tax and lose another £20 due to the tapered Personal Allowance. This creates an effective marginal rate of 60% (or 67.5% in Scotland).

Taxable pension withdrawals count towards adjusted net income. So, if you take a large lump sum from your pension, this could push your total income over £100,000, triggering the 60% rate.

Instead, consider spreading taxable withdrawals across tax years, using available allowances and reliefs, and coordinating your pension income with other sources of income.

4. Failing to prepare for upcoming changes to Inheritance Tax on pensions

Currently, unused pension funds are usually exempt from IHT, making them an effective way to pass wealth on tax-efficiently. 

However, from 6 April 2027, most unused pensions and death benefits will be included in the value of your estate for IHT purposes.

This is a major reform which could have a significant impact on your retirement and estate plans. 

Indeed, failing to review and update your plans in line with the new rules could leave your family facing an unexpected – or higher-than-expected – IHT bill, reducing the amount of wealth they receive.

There could be further changes to tax legislation announced in John Healey’s first Budget on 28 October. Keep an eye out for our update on the day to find out whether there are any reforms that could affect your long-term financial plan.

We can help you keep your retirement wealth as tax-efficient as possible

Retirement should be a time to enjoy the wealth you’ve worked hard to build over the years, not to be haunted by avoidable tax bills.

However, navigating tax rules and effectively coordinating different sources of income can be frighteningly complex.

We can help you identify potential tax traps and take steps to avoid them before they become a problem.

Our financial planners can use sophisticated software to model different income strategies, allowing you to make informed decisions and keep more of your wealth working for you.

To find out more about how we can help you plan financially for retirement, please email hello@bluewealth.co.uk or call us on 0117-332 0230.

Please note

The content of this newsletter is offered only for general informational and educational purposes. It is not offered as, and does not constitute, financial advice.

Blue Wealth is not responsible for the accuracy of the information contained within linked sites.

Please do not act based on anything you might read in this article. All contents are based on our understanding of HMRC legislation, which is subject to change.

The Financial Conduct Authority does not regulate estate planning, cashflow planning, or tax planning.

A pension is a long-term investment not normally accessible until 55 (57 from April 2028). The fund value may fluctuate and can go down, which would have an impact on the level of pension benefits available. Past performance is not a reliable indicator of future performance. 

The tax implications of pension withdrawals will be based on your individual circumstances. Thresholds, percentage rates, and tax legislation may change in subsequent Finance Acts. 

Workplace pensions are regulated by The Pensions Regulator.
Father’s Day: 3 smart ways to protect your family’s financial future

Every year, on 21 June, families around the UK celebrate Father’s Day. It’s a great opportunity to show appreciation for your dad while also celebrating and reflecting on being a parent yourself.

Perhaps you thought back to cherished memories and marvelled at how fast your children have grown? Maybe you were showered with cards and gifts? However, you spent this special day, it serves as an important reminder to consider what may lie ahead.

Indeed, as a parent, one of your most important responsibilities is planning for your family’s financial future.

So, with Father’s Day still fresh in your mind, keep reading to discover three smart ways you could create a financial safety net to protect your family.

1. Put life insurance in place

Nobody likes to imagine the worst-case scenario, but as a parent, it’s important to plan for the unexpected.

Taking out appropriate life insurance ensures that your family can afford to cover their essential living costs if you die. This may be especially meaningful if you’re the sole or primary breadwinner.

Your loved ones could also use a payout to clear outstanding debts, such as mortgages or school fees, helping to reduce financial and emotional pressure at this difficult time.

There are several types of cover to consider; some pay a lump sum, while others make regular payments that either increase or decrease over time. A financial planner can explain your options and support you in choosing a policy that suits your specific needs and those of your family.

You might also want to consider writing your life insurance into a trust so that any payout is made directly to your beneficiaries, rather than forming part of your estate. The potential benefits of this include:

  • Your family receives money from the policy straight away and avoids a potentially lengthy probate process.
  • The life insurance payout is not included in Inheritance Tax calculations, so your loved ones receive the full amount.

However, this is not the right approach for everyone, so it’s crucial to seek professional advice before making any decisions about your life insurance cover.

2. Set up Lasting Powers of Attorney

Without appropriate legal documentation in place, your family may be unable to access accounts or make important decisions about your finances and wellbeing if you lose the mental capacity to do so.

This could mean they struggle to pay essential bills, which may lead to penalties for missed payments and disruption to services they rely on at a time when they need stability the most.

Moreover, your family will likely have to apply to the Court of Protection to obtain the legal right to manage your affairs, which can be time-consuming, costly, and emotionally draining.

To protect your family from this challenging situation, you could set up Lasting Powers of Attorney (LPA). These are legally binding documents that allow you to appoint a trusted person or people (your “attorneys”) to make decisions on your behalf if you become unable to do so.

There are two types of LPA:

  • Property and financial affairs – This covers decisions about your money and property, such as paying bills and managing your bank accounts.
  • Health and welfare – This covers decisions about how you live and are cared for, such as your daily routine and life-sustaining treatment.

At Blue Wealth, we can help you embed LPAs in your broader financial plan, so that your family receives the support they need if you’re no longer able to provide it.

3. Build an emergency fund

An emergency fund provides a vital financial buffer if you or your family experience an unexpected shock, such as redundancy or medical costs. This money could ensure that:

  • Your family’s routine and sense of security are protected
  • You don’t need to immediately dip into your savings
  • You can avoid expensive borrowing.

It’s widely recommended that you hold enough savings to cover around three to six months of essential expenses. However, this is a general rule of thumb, and it’s important to consider your specific circumstances and needs when deciding how much is “enough” for your family.

For example, you may want to save more if you have several children or other family members who are financially dependent on you.

You might find it helpful to set up automated monthly payments so that a portion of your salary goes into a savings account that you can easily access in an emergency.

Get in touch

If you’re a parent who would like help creating a financial plan that provides for your family’s future, we’d love to hear from you.

To find out more, please email hello@bluewealth.co.uk or call us on 0117 332 0230.

Please note

The content of this newsletter is offered only for general informational and educational purposes. It is not offered as, and does not constitute, financial advice.

Blue Wealth Ltd is not responsible for the accuracy of the information contained within linked sites.

The Financial Conduct Authority does not regulate estate planning or Lasting Powers of Attorney.

Note that life insurance and financial protection plans typically have no cash in value at any time and cover will cease at the end of the term. If premiums stop, then cover will lapse.

Cover is subject to terms and conditions and may have exclusions. Definitions of illnesses vary from product provider and will be explained within the policy documentation.

Approved by Best Practice on: 24/6/2026

Team update: Your end-of-year round-up and our Christmas opening hours

Phew! The Blue Wealth team has packed a lot into 2025, and we’re extremely proud of our achievements.

It’s been great supporting you throughout the year. We’ve also enjoyed meeting some of you at our social events.

As the festive season approaches, now is a great time to reflect on this year’s highlights. So, here’s an end-of-year round-up (along with details of our Christmas office opening hours).

Blue Wealth’s 2025 highlights

Here are just a few of our favourite moments from 2025.

Inclusion in the New Model Adviser Top 100 for the second year running

The Citywire New Model Adviser Top 100 is an annual list that celebrates the best of the professional planning community.

Only firms that deliver the highest standards of service and demonstrate innovation, client-centred approaches, and outstanding contributions to the financial advice sector are included.

And we’ve made the list two years in a row!

Supporting two local charities

We’re passionate about supporting local causes, and in 2025, we helped two charities raise valuable funds to continue their important work.

Community of Purpose is an award-winning not-for-profit social enterprise that aims to provide support and meaningful opportunities to young, hard-to-reach people in Bristol.

The Anchor Society, our current charity partner, improves the lives of older people in the Greater Bristol area by offering grants to individuals facing financial difficulties.

We will make a £50 donation to The Anchor Society for every initial meeting we have that comes from a client recommendation.

Read more: Our charity incentive

Expanding the Blue Wealth team

We love to see the Blue Wealth team grow and take on new talent. So, we were delighted to welcome Tom Fraser as a trainee paraplanner in November.

Tom has worked in financial services since graduating from university in 2019 and is currently studying to become a fully Chartered paraplanner.

Hosting two successful client events

We love hosting social events for our clients and the Blue Wealth team. They’re a great opportunity to meet and chat in a relaxed environment. This year, we held two well-attended events.

On 20 April, we booked a table of 12 at the Bristol Bears Rugby Club. A few of the Blue Wealth team went, along with several clients and contacts. Unfortunately, Bristol lost, but the weather was good, and we all had a fantastic day out.

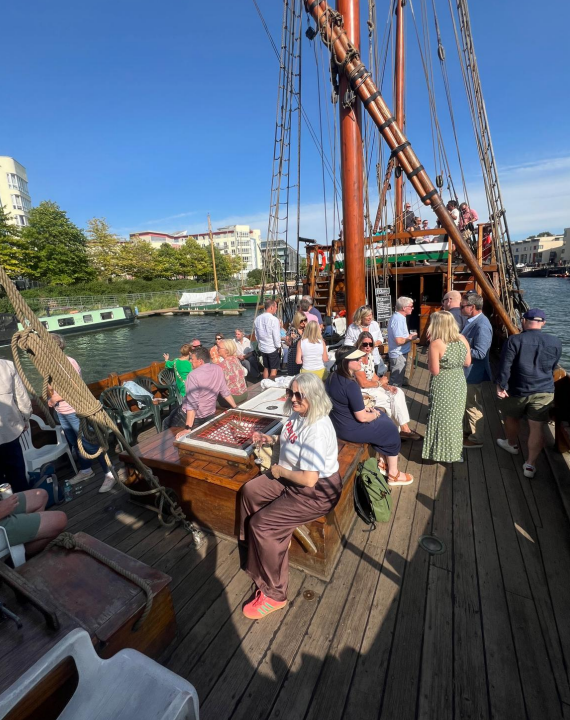
On Thursday 3 July, a group of 40 clients and members of the Blue Wealth team enjoyed a late afternoon sail along the water aboard The Matthew in Bristol’s historic floating harbour. The weather was great, the food delicious, and the company fantastic.

Achieving Cyber Essentials certification

In October, after months of hard work by the whole team and our IT partners, we were awarded Cyber Essentials certification.

This demonstrates our commitment to protecting you by maintaining the most up-to-date and thorough IT standards.

Enjoying a team trip to Barcelona

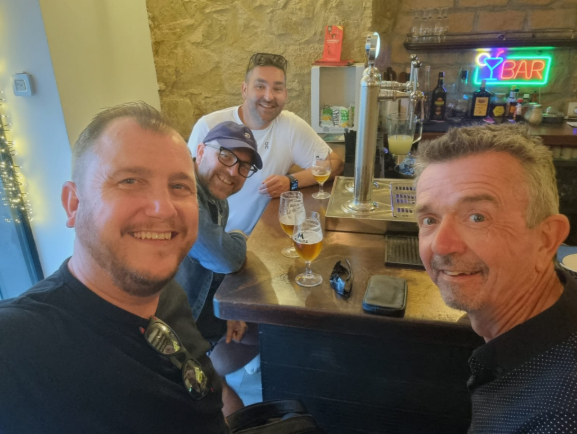
In April, Adrian, Dan, Rob, and Nathan went on a two-night city break to Barcelona in Spain to celebrate the company’s ongoing success.

Nathan said, “It was a brilliant trip. We packed so much into a few days, and it was great to spend time together outside the office.”

Our Christmas office opening hours and season’s greetings to you all

As you can see, we’ve had a busy year, so the team will be taking a well-deserved break over the festive period.

The office will be unattended from 12 pm on Wednesday 24 December until Friday 2 January. However, we will check emails and phone messages periodically during these times.

We’d like to wish you all a merry Christmas and a happy new year. We hope you have a relaxing break and look forward to seeing you in 2026!

Get in touch

If you’d like to kick off the new year on the right financial footing, the Blue Wealth team is here to help.

Please email hello@bluewealth.co.uk or call us on 0117 332 0230.

Please note

The content of this newsletter is offered only for general informational and educational purposes. It is not offered as, and does not constitute, financial advice.

3 myths and misunderstandings about wills and probate – busted

Having an up-to-date and valid will is a crucial part of financial planning.

A poorly drafted document, or one that has not been amended to reflect changes in your circumstances, could mean that your estate is not passed on in line with your wishes.

Unfortunately, there are many common myths and misconceptions about wills that could lead to mistakes which may negatively affect your beneficiaries.

For example, a Will Aid survey of more than 2,000 UK adults found that 56% of respondents were unaware that, in England and Northern Ireland, marriage typically revokes a will unless you state otherwise.

Likewise, misunderstandings about probate – the process by which a deceased person’s estate is administered – could result in family disputes, delays, and poor decisions.

Read on to learn the truth behind three myths and misunderstandings about wills and probate, to help you avoid common mistakes and take control of how your estate is managed after you’re gone.

1. Only the wealthy need a will

You might feel that a will is unnecessary because your estate is relatively “small”. However, once you add up the value of everything you own (the equity in your home, pensions, savings, investments, insurance payouts, personal belongings, and so on), you might be surprised by how much your estate is worth. This could be a significant inheritance for your surviving family.

Moreover, the purpose of a will isn’t just to pass on your wealth. It also allows you to take control of matters such as:

  • How your digital and online assets are managed
  • Who oversees the distribution of your estate
  • How your business should be run and by whom
  • Who will care for your children and pets
  • Your funeral arrangements.

In contrast, if you die without a will, your estate will be distributed in line with the rules of intestacy. This means that the courts will decide how your estate is distributed, which might not be what you intended and could cause unnecessary distress and financial hardship for your beneficiaries.

2. My spouse or civil partner will automatically inherit everything, so I don’t need a will

As mentioned above, if you die without a will, your estate will be passed on in accordance with the rules of intestacy. This doesn’t necessarily mean that your spouse or civil partner will inherit all your assets after your death.

How your estate is distributed will depend on your circumstances and where you live in the UK – the rules vary between England and Wales, Scotland, and Northern Ireland. That’s why it’s crucial to seek professional advice to ensure you understand the laws that apply to you.

According to Citizens Advice, in England and Wales, if you have no children, your spouse or civil partner will typically inherit everything.

However, if you do have children and your estate is valued at more than £322,000 (2025/26), your spouse or civil partner will inherit:

  • All your personal property and belongings
  • The first £322,000 of your estate
  • Half of the remaining estate.

All your children will inherit equal shares of the remaining half of the estate. This includes any biological or adopted children from previous relationships.

Remember also that in most cases, a marriage or civil partnership automatically revokes any will you made before the union took place. As such, it’s crucial to write a new will that includes your spouse or partner – and any other beneficiaries – if you want your estate to be passed on according to your wishes.

3. Probate is always required

Probate gives an individual the legal right to deal with your estate after you die. It typically takes around 12 weeks for probate to be granted once an application has been submitted to the probate registry, but it can take much longer.

Figures published by Which? reveal that the number of probate applications taking more than 12 months rose by 134% between 2020 and 2023.

However, probate is not always required.

Government guidelines state that probate isn’t necessary if the person who died:

  • Only had savings
  • Owned shares or money with others, as they will automatically pass to the surviving owners unless they have agreed otherwise
  • Owned land or property as “joint tenants” with others, as it automatically passes to the surviving owners.

As such, if you’re named in someone’s will as a beneficiary when they pass away, don’t assume that probate is needed. You might find that you can avoid this potentially lengthy and stressful process.

Please note

The content of this newsletter is offered only for general informational and educational purposes. It is not offered as, and does not constitute, financial advice.

Blue Wealth Ltd is not responsible for the accuracy of the information contained within linked sites.

Blue Wealth Ltd is an appointed representative of Best Practice IFA Group Ltd, which is authorised and regulated by the Financial Conduct Authority.

The Financial Conduct Authority does not regulate will writing.

Approved by Best Practice IFA Group:

Your complete guide to the Bounce Back loan scheme

Cash machine and £5 note

Last month, the government announced a brand-new loan scheme to support businesses through the coronavirus pandemic.

Announcing the package of measures, the Chancellor said: “Small businesses will play a key role creating jobs and securing economic growth as we recover from the coronavirus pandemic. The Bounce Back loan scheme will make sure they get the finance they need – helping them bounce back and protect jobs.”

Applications for the Bounce Back loan scheme open today (4th May 2020), so here’s what you need to know if you’re considering taking advantage of the support.

What you need to know about the Bounce Back loan scheme

  • Under the scheme, your business can apply for a loan from £2,000 up to a maximum of 25% of your business’ annual turnover, or £50,000, whichever is lower
  • Lenders benefit from a 100% government guarantee against the outstanding balance of the finance
  • The loans are interest-free for a year, with the government covering the first 12 months of interest through a Business Interruption Payment (BIP). After the first year, you will pay interest at a rate of 2.5% per year
  • Loans will be taken over six years, but you can repay early at any time with no early repayment charge
  • Lenders are not permitted to take personal guarantees or take recovery action over your personal assets (such as your main home or personal vehicle).

You will not have to begin principal repayments for the first 12 months, and neither businesses nor lenders have to pay a fee to access the scheme.

Bounce Back loan eligibility criteria

Credit institutions, public sector bodies, insurance companies and state-funded primary or secondary schools are not eligible to apply. Otherwise, businesses from all sectors can make an application for a Bounce Back loan.

You must self-certify and confirm that:

  • You are a UK-based business established before 1 March 2020
  • You have been adversely affected by the coronavirus pandemic
  • You are not currently using a government-backed coronavirus loan scheme
  • You were not a ‘business in difficulty’ at 31st December 2019
  • Your business is not in bankruptcy, liquidation or undergoing debt restructuring
  • 50% of the income of your business is derived from its trading activity (not required if the borrower is a charity or a further education college).

Steven Jones, chief executive of UK Finance, says that while affordability checks would ‘be lighter’, firms should still ‘think very carefully about their ability to repay the loan’.

That is because, despite the government guarantee, banks are required to first chase firms for money if they do not repay the loan. As a borrower, you will always remain 100% liable for the debt.

Mr Jones said: “These are loans, not grants, so if a business is already indebted and taking on further debt, they should think carefully before making an application.”

How to apply for a Bounce Back Loan

Your first step is to find a lender. Accredited lenders are listed on the British Business bank website. As of 10am on Monday 4th May, accredited lenders included: Bank of Scotland, Barclays, Danske Bank, Lloyds Bank, NatWest, Santander, RBS, HSBC, Ulster Bank, Yorkshire Bank and Clydesdale Bank.

You should approach a lender yourself, ideally via the lender’s website. Approach your own provider in the first instance, although you may also consider approaching other lenders if you are unable to access the finance you require.

The online application is seven questions long and you will have to self-certify that your business is eligible for a loan under the Bounce Back loan scheme.

Lenders do not need to carry out any credit checks or verify the long-term viability of firms.

Note that if one lender turns you down, you can still approach other lenders within the scheme.

Once your loan has been approved, the government has previously said that most businesses will get the finance within 24 hours. The British Business Bank said money will be received ‘within days’.

What if I already have a coronavirus Business Interruption Loan?

You can’t apply for the Bounce Back loan scheme if you already have a coronavirus Business Interruption Loan unless the Bounce Back loan will refinance the whole of your existing facility.

However, you can transfer a coronavirus Business Interruption Loan of up to £50,000 to the Bounce Back loan scheme before 4th November 2020.

Following the launch of the Bounce Back loan scheme, the minimum coronavirus Business Interruption Loan has been increased to £50,001.

Get in touch

If you need any more advice concerning your business or personal finances during these uncertain times, please get in touch.

Please note

The above is offered only for general informational and educational purposes. It is not offered as and does not constitute financial advice. The information has been taken from a verified source and was correct at the time of issue.